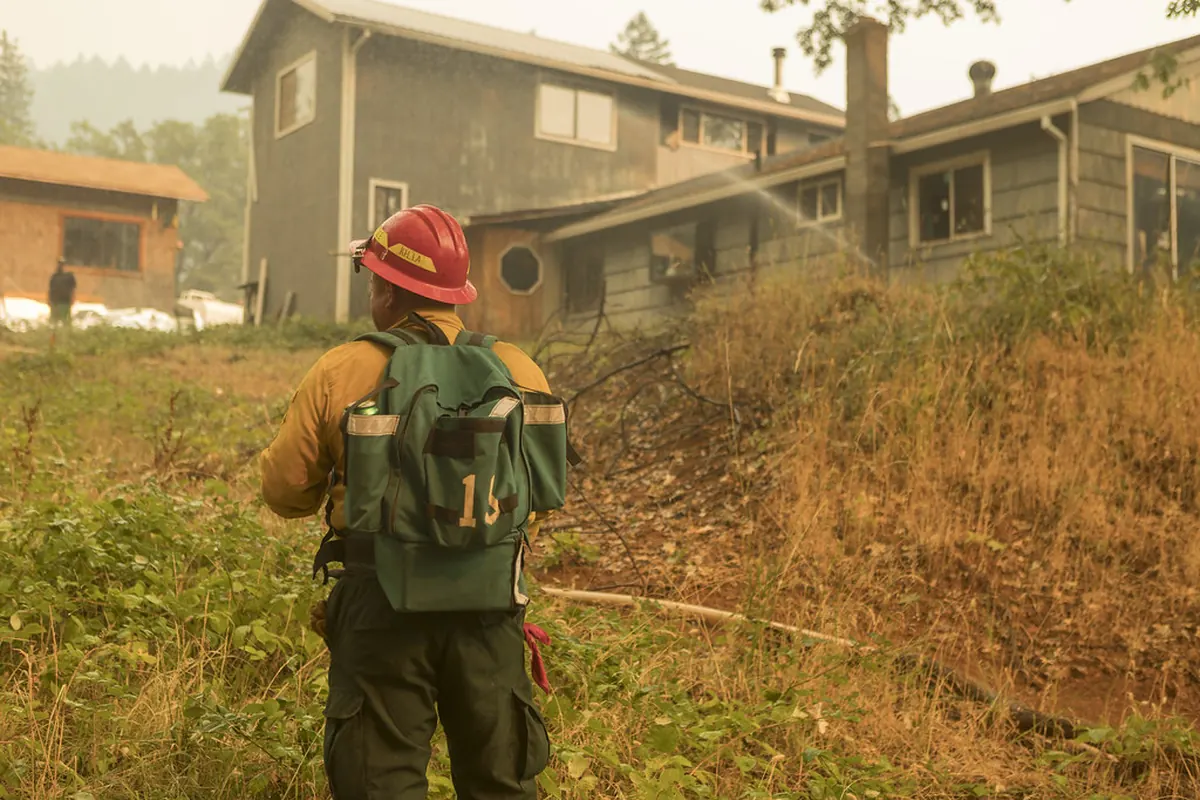
Losing a home to wildfire is overwhelming. In the weeks after the 2023 Gray and Oregon Road fires near Spokane, and after the Carlton Complex and Malden fires before them, families had to make insurance decisions while dealing with displacement and grief. This checklist is meant to make the claim side a little more manageable.
First steps
- Report the claim and get a claim number and adjuster contact.
- Ask for a complete copy of your policy, including all endorsements and the declarations page.
- Ask about an advance on additional living expenses and contents.
- Start a claim log of every call, email and payment.
Coverage A: is the limit enough?
Compare your dwelling limit with real rebuild costs. Post-fire demand for contractors and current code requirements can push costs up. Check whether you have extended replacement cost, which pays a set percentage above the limit, and ordinance or law coverage for code upgrades. Our wildfire total-loss coverage check helps you test the numbers.
Contents
A full inventory after a total loss is a huge task. Ask the insurer whether it will accept a partial inventory or pay part of the contents limit without one. Use photos, videos, bank and credit card records and online order histories to rebuild your list room by room.
Additional living expenses
ALE covers the extra cost of living elsewhere: rent, increased food costs, mileage and more. Keep every receipt, and ask how long ALE lasts and whether it has a dollar limit.
Debris removal and site work
Ash, burned materials and hazardous debris must be removed before rebuilding. Policies often have a separate or limited debris removal amount. Ask how your policy handles it, and whether government cleanup programs apply.
Rebuild or buy elsewhere?
Some policies let you rebuild on another lot or buy an existing home and still collect replacement cost, sometimes with limits. Get the insurer’s position in writing before you decide.
When numbers don’t match
If the insurer’s rebuild estimate is well below contractor bids, an estimate review or appraisal may help with the amount. If the dispute is about limits, policy terms or how the claim is being handled, contact the OIC’s consumer advocates or a Washington attorney.
Keep reading
 Guide
Frozen Pipes and Ice Dams: What Washington Policies Usually Say
How policies usually treat winter water damage, and the conditions insurers tend to raise.Read Guide
How to Read Your Insurer’s Estimate Line by Line
Line items, quantities, depreciation and O&P, and where the gaps usually hide.Read Guide