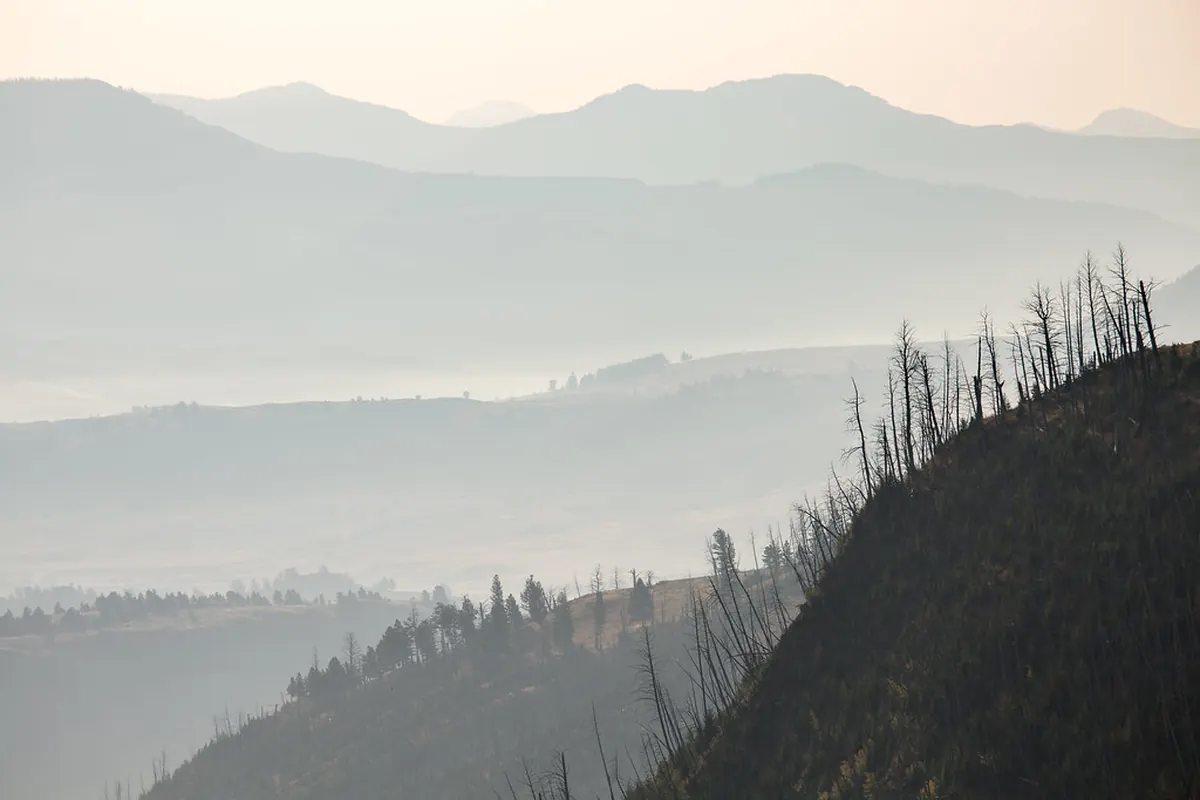
Wildfire in Washington
Washington’s largest wildfires have mostly burned east of the Cascade crest, where hot, dry summers meet grass, sagebrush and pine forest. The 2014 Carlton Complex destroyed hundreds of homes in Okanogan County. On Labor Day 2020, the Babb Road Fire swept through the town of Malden in Whitman County. In August 2023, the Gray Fire near Medical Lake and the Oregon Road Fire north of Spokane destroyed hundreds of homes within days. The 2015 Sleepy Hollow Fire showed that fire can reach neighborhoods in Wenatchee too.
Total losses: is the limit enough?
When a home is destroyed, the first question is often whether Coverage A is high enough to rebuild. Construction costs, code requirements and post-fire demand for contractors can push the rebuild price above a limit set years earlier. Extended replacement cost endorsements can help. Our wildfire total-loss coverage check lets you test the numbers yourself.
Partial losses and smoke
Homes that survive a wildfire can still have serious damage: ash in attics and ducts, smoke odor in insulation, heat-damaged siding and windows, and landscaping lost. These claims are often underpaid because the house looks intact from the street.
- Professional cleaning of HVAC systems, attics and wall cavities.
- Replacement of heat-damaged windows, vinyl siding and roof components.
- Contents cleaning or replacement for soft goods and electronics.
- Debris removal and hazardous material handling for total losses.
- Additional living expenses during evacuation and repairs.
Frequently asked questions
Do I have to rebuild on the same lot to get full replacement cost?
Policies differ. Some let you rebuild elsewhere or buy a replacement home, sometimes with limits. Read the loss settlement section and ask the insurer to confirm in writing.
What if my contents were all destroyed?
Some insurers will pay part of the contents limit without a full itemized inventory after a total loss. Ask the insurer what it allows and get the answer in writing.
Is smoke damage from a fire miles away covered?
Smoke from a wildfire is generally a covered fire-related loss under most homeowner policies, subject to policy terms. The dispute is usually how much cleaning or replacement is needed.
Related services
 Related service
Snow, Ice Dam & Freeze Appraisal
Roof collapse, ice dams, frozen pipes and ice-storm damage from Washington’s winter weather.Learn more Related service
Carrier Estimate Review
A line-by-line review of the insurer’s estimate before you decide whether to supplement or demand appraisal.Learn more Related service