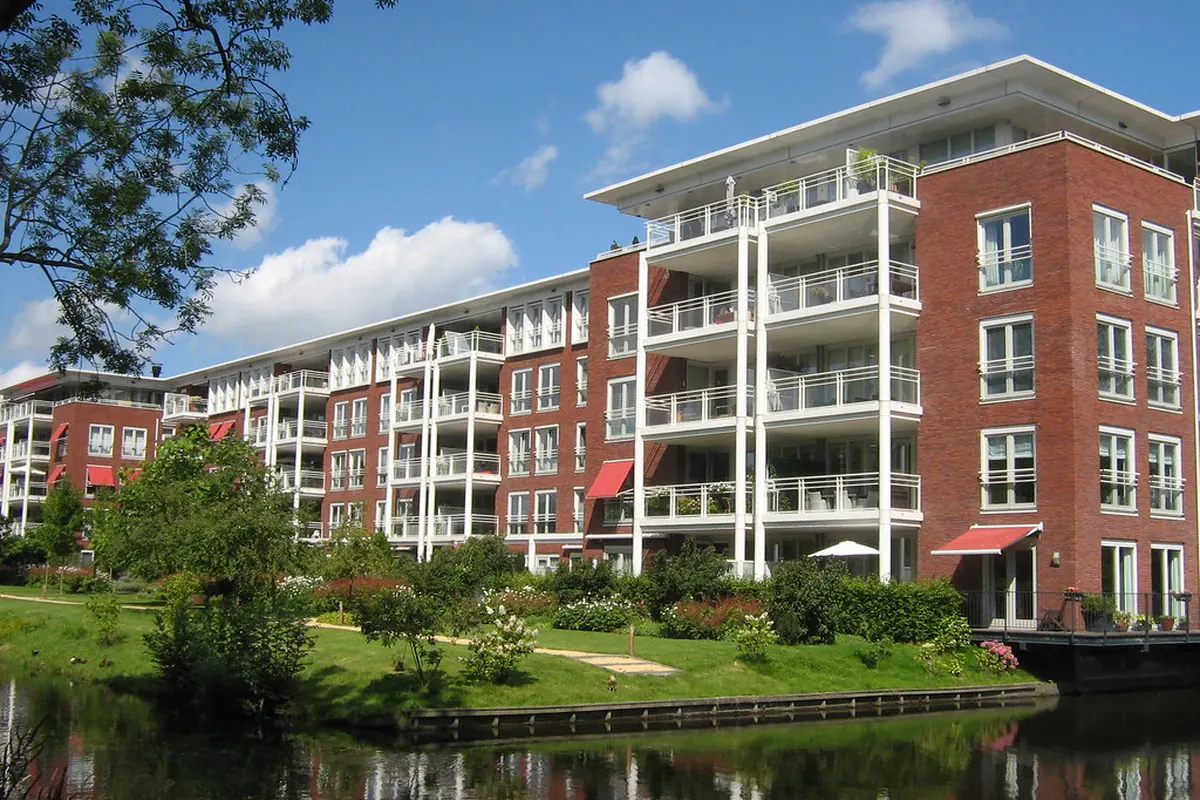
Why larger losses need a different approach
A windstorm across a Kitsap County condominium complex or a sprinkler failure in a Kent warehouse isn’t a bigger house claim. It involves multiple buildings, commercial roofing systems, fire and life-safety code, specialized trades and often a business that can’t operate until the work is done.
Washington has a large stock of condominium buildings, many in the Puget Sound region. When a loss hits, the association’s board has to manage the master policy, unit owners’ HO-6 claims, the property manager and contractors at the same time. A clear, defensible valuation keeps that process moving.
What we bring to commercial panels
- Building-by-building scopes with consistent measurements and photo logs.
- Commercial roofing knowledge: TPO, PVC, built-up, modified bitumen and standing-seam metal.
- Code and permit analysis, including energy code requirements that apply when roofs or envelopes are replaced.
- Coordination with forensic engineers, building envelope consultants and contractors.
- Clear separation of building, business personal property and time-element items for the award.
Condominium associations
Boards often discover after a loss that the master policy has a high deductible, a coinsurance clause or a separate earthquake form. We help the board understand how those terms affect what it collects, then value the covered portion carefully. Where unit owners also have claims, we keep the two scopes from overlapping.
Frequently asked questions
Can an appraisal panel decide business interruption amounts?
If the policy’s appraisal clause applies to the time-element coverage and the disagreement is about amount, it may. Some forms limit it. We read the specific language first.
Does the board have to vote to invoke appraisal?
That depends on the association’s governing documents and management agreement. Many boards authorize it by resolution so the decision is on record.
Do you work with public adjusters and attorneys on commercial files?
Yes. We often serve as appraiser on files where a public adjuster or attorney represents the owner on other issues.
Related services
 Related service
Roof & Hail Damage Appraisal
Shingle, metal, tile and low-slope roof disputes over slopes, repairability, steep charges and code items.Learn more Related service
Windstorm & Tornado Appraisal
Pacific windstorms, bomb cyclones and the occasional tornado: torn roofs, siding, fences and outbuildings.Learn more Related service